Key Takeaways:
There's no dedicated EPF withdrawal for solar panels, but you can use your Akaun Fleksibel savings for any purpose, from RM50 upwards and with no documents. Akaun Sejahtera's housing withdrawals don't cover home improvements like solar. Before you withdraw, weigh the dividend you give up, 6.15% for 2025, against what the panels would save on your TNB bill.
Your EPF statement shows a balance you can't touch for decades, and your TNB bill keeps climbing. Can the first pay for a fix to the second?
Partly. EPF has no withdrawal scheme for solar panels, but since May 2024 every member under 55 has had an account they can withdraw from for any reason. Whether you should is a different question, because that money stops earning dividends the day it leaves EPF.
Below, you'll find which EPF account can pay for solar, how much you're likely to have in it, what the withdrawal really costs you, and cheaper ways to go solar without touching your retirement savings.
Can You Withdraw EPF to Pay for Solar Panels?
Yes, but only from Akaun Fleksibel, which you can withdraw for any purpose; the other 2 EPF accounts can't be used for solar. Since 11 May 2024, contributions for members under 55 are split across 3 accounts, according to StashAway's EPF withdrawal guide:
| Account | Share of contributions | Can it pay for solar? | What it's for |
|---|---|---|---|
| Akaun Persaraan | 75% | No | Locked until age 55 |
| Akaun Sejahtera | 15% | No | Buying, building or reducing a housing loan, education, healthcare, Hajj and the age 50 withdrawal |
| Akaun Fleksibel | 10% | Yes | Any purpose, any time, from RM50, with no documents |
Source: StashAway EPF withdrawal guide (October 2026), based on KWSP rules. Check KWSP for the latest terms.
Akaun Sejahtera's housing withdrawals are tied to buying, building or paying down a home, not improving one, so installing solar doesn't qualify. Akaun Fleksibel is the only route.
How Much Could Your Akaun Fleksibel Cover?
For most salaried homeowners, Akaun Fleksibel builds up slowly: about RM1,100 to RM2,200 a year on salaries of RM4,000 to RM8,000. Here's what flows in, assuming the standard 11% employee contribution:
| Monthly salary | Employer rate | Into Akaun Fleksibel each month | After 1 year | After 5 years |
|---|---|---|---|---|
| RM4,000 | 13% | RM96 | RM1,152 | RM5,760 |
| RM6,000 | 12% | RM138 | RM1,656 | RM8,280 |
| RM8,000 | 12% | RM184 | RM2,208 | RM11,040 |
Illustrative calculation: 11% employee plus 12% or 13% employer contributions, 10% of the total allocated to Akaun Fleksibel, before dividends.
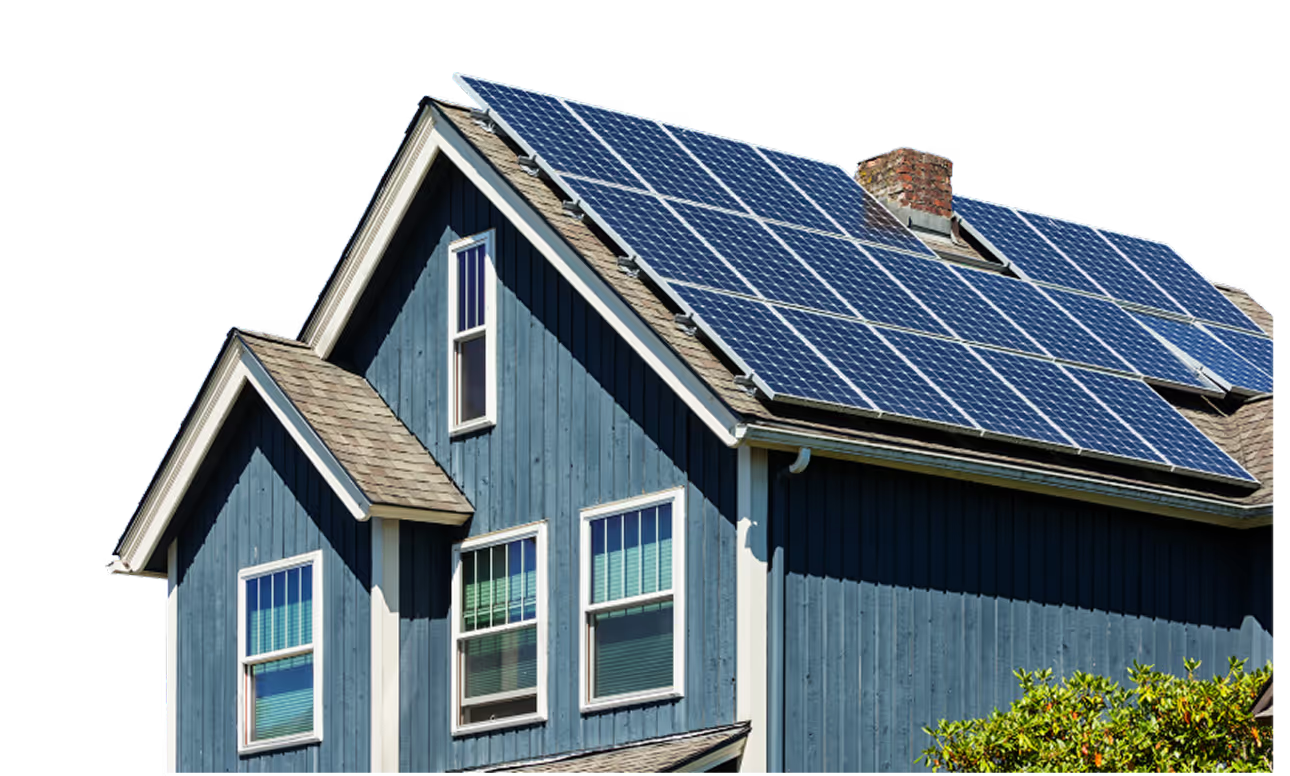
Compare that with what a system costs. A 5 kWp system runs around RM17,000 installed, according to our solar panel price list. For most households, Akaun Fleksibel covers part of the bill rather than all of it.
What Does Withdrawing EPF Really Cost You?
Every ringgit you withdraw stops earning EPF's dividend, which was 6.15% for 2025, according to Bernama. Withdraw RM10,000 and you give up around RM615 in dividends in the first year alone, and more each year after as compounding builds.
On paper, solar can earn more than that. Our solar payback guide works through a RM25,000 system that saves RM350 a month, a return of roughly 17% a year. RM10,000 of that system would account for around RM140 a month in savings, more than double what the same money earns in EPF.
The trade-off is certainty. EPF dividends compound for your retirement, while solar savings depend on how much electricity you use, your roof and future tariffs. And unlike EPF, money spent on panels doesn't sit in an account you can draw on at 55.
Are There Better Ways to Pay for Solar Than EPF?
Yes. Most homeowners can go solar without touching their EPF at all:
| Option | Upfront cost | Keeps your EPF intact? |
|---|---|---|
| SuRIA Home rebate | Cuts the system price by up to RM3,000 | Yes |
| Rent-to-Own | RM 0 | Yes |
| Bank solar loan | Low or none | Yes |
| Akaun Fleksibel withdrawal | Paid from your EPF savings | No |
Rebate terms per the SuRIA Home programme; check eligibility and deadlines before you apply.
The SuRIA Home rebate cuts the upfront price, while Rent-to-Own removes it entirely and bundles maintenance. Our comparison of solar financing options in Malaysia sets out the long-term cost of each.
How Do You Withdraw From Akaun Fleksibel?
You can withdraw online in a few minutes, with no supporting documents. The process takes 4 steps:
- Log in to the KWSP i-Akaun app or the i-Akaun (Member) portal.
- Select Akaun Fleksibel and choose the withdrawal option.
- Enter an amount of at least RM50 and your bank account details.
- Confirm with the code sent to your registered phone number.
Larger withdrawals, above RM3,000, may need a thumbprint check at an EPF branch. If you plan to combine EPF with other funding, withdraw only the gap you need rather than emptying the account.
For a deeper look at how quickly a system pays for itself, see our solar payback period guide for Malaysia.
Keep Your Retirement Money Working
You can use Akaun Fleksibel to pay for solar, but it usually covers only part of a system and costs you EPF's dividend on every ringgit you take out. Use it to close a small gap, not to fund the whole system.
If you'd rather leave your EPF untouched, GetSolar's Rent-to-Own plan lets you start at RM 0 upfront, with maintenance included, so your bill drops while your retirement savings keep compounding.
Check out our solar calculator or chat with the team on WhatsApp whenever you're ready.

Rent-to-Own Solar. RM0 Upfront cost. Guaranteed Savings
Immediate ROI

Rent-to-Own Solar. RM0 Upfront cost. Guaranteed Savings
(10-Year RTO plan)
+ 10-Year Free Maintenance

Be part of The Solar Collective, where we share the latest updates, tips, and discussions on solar energy.